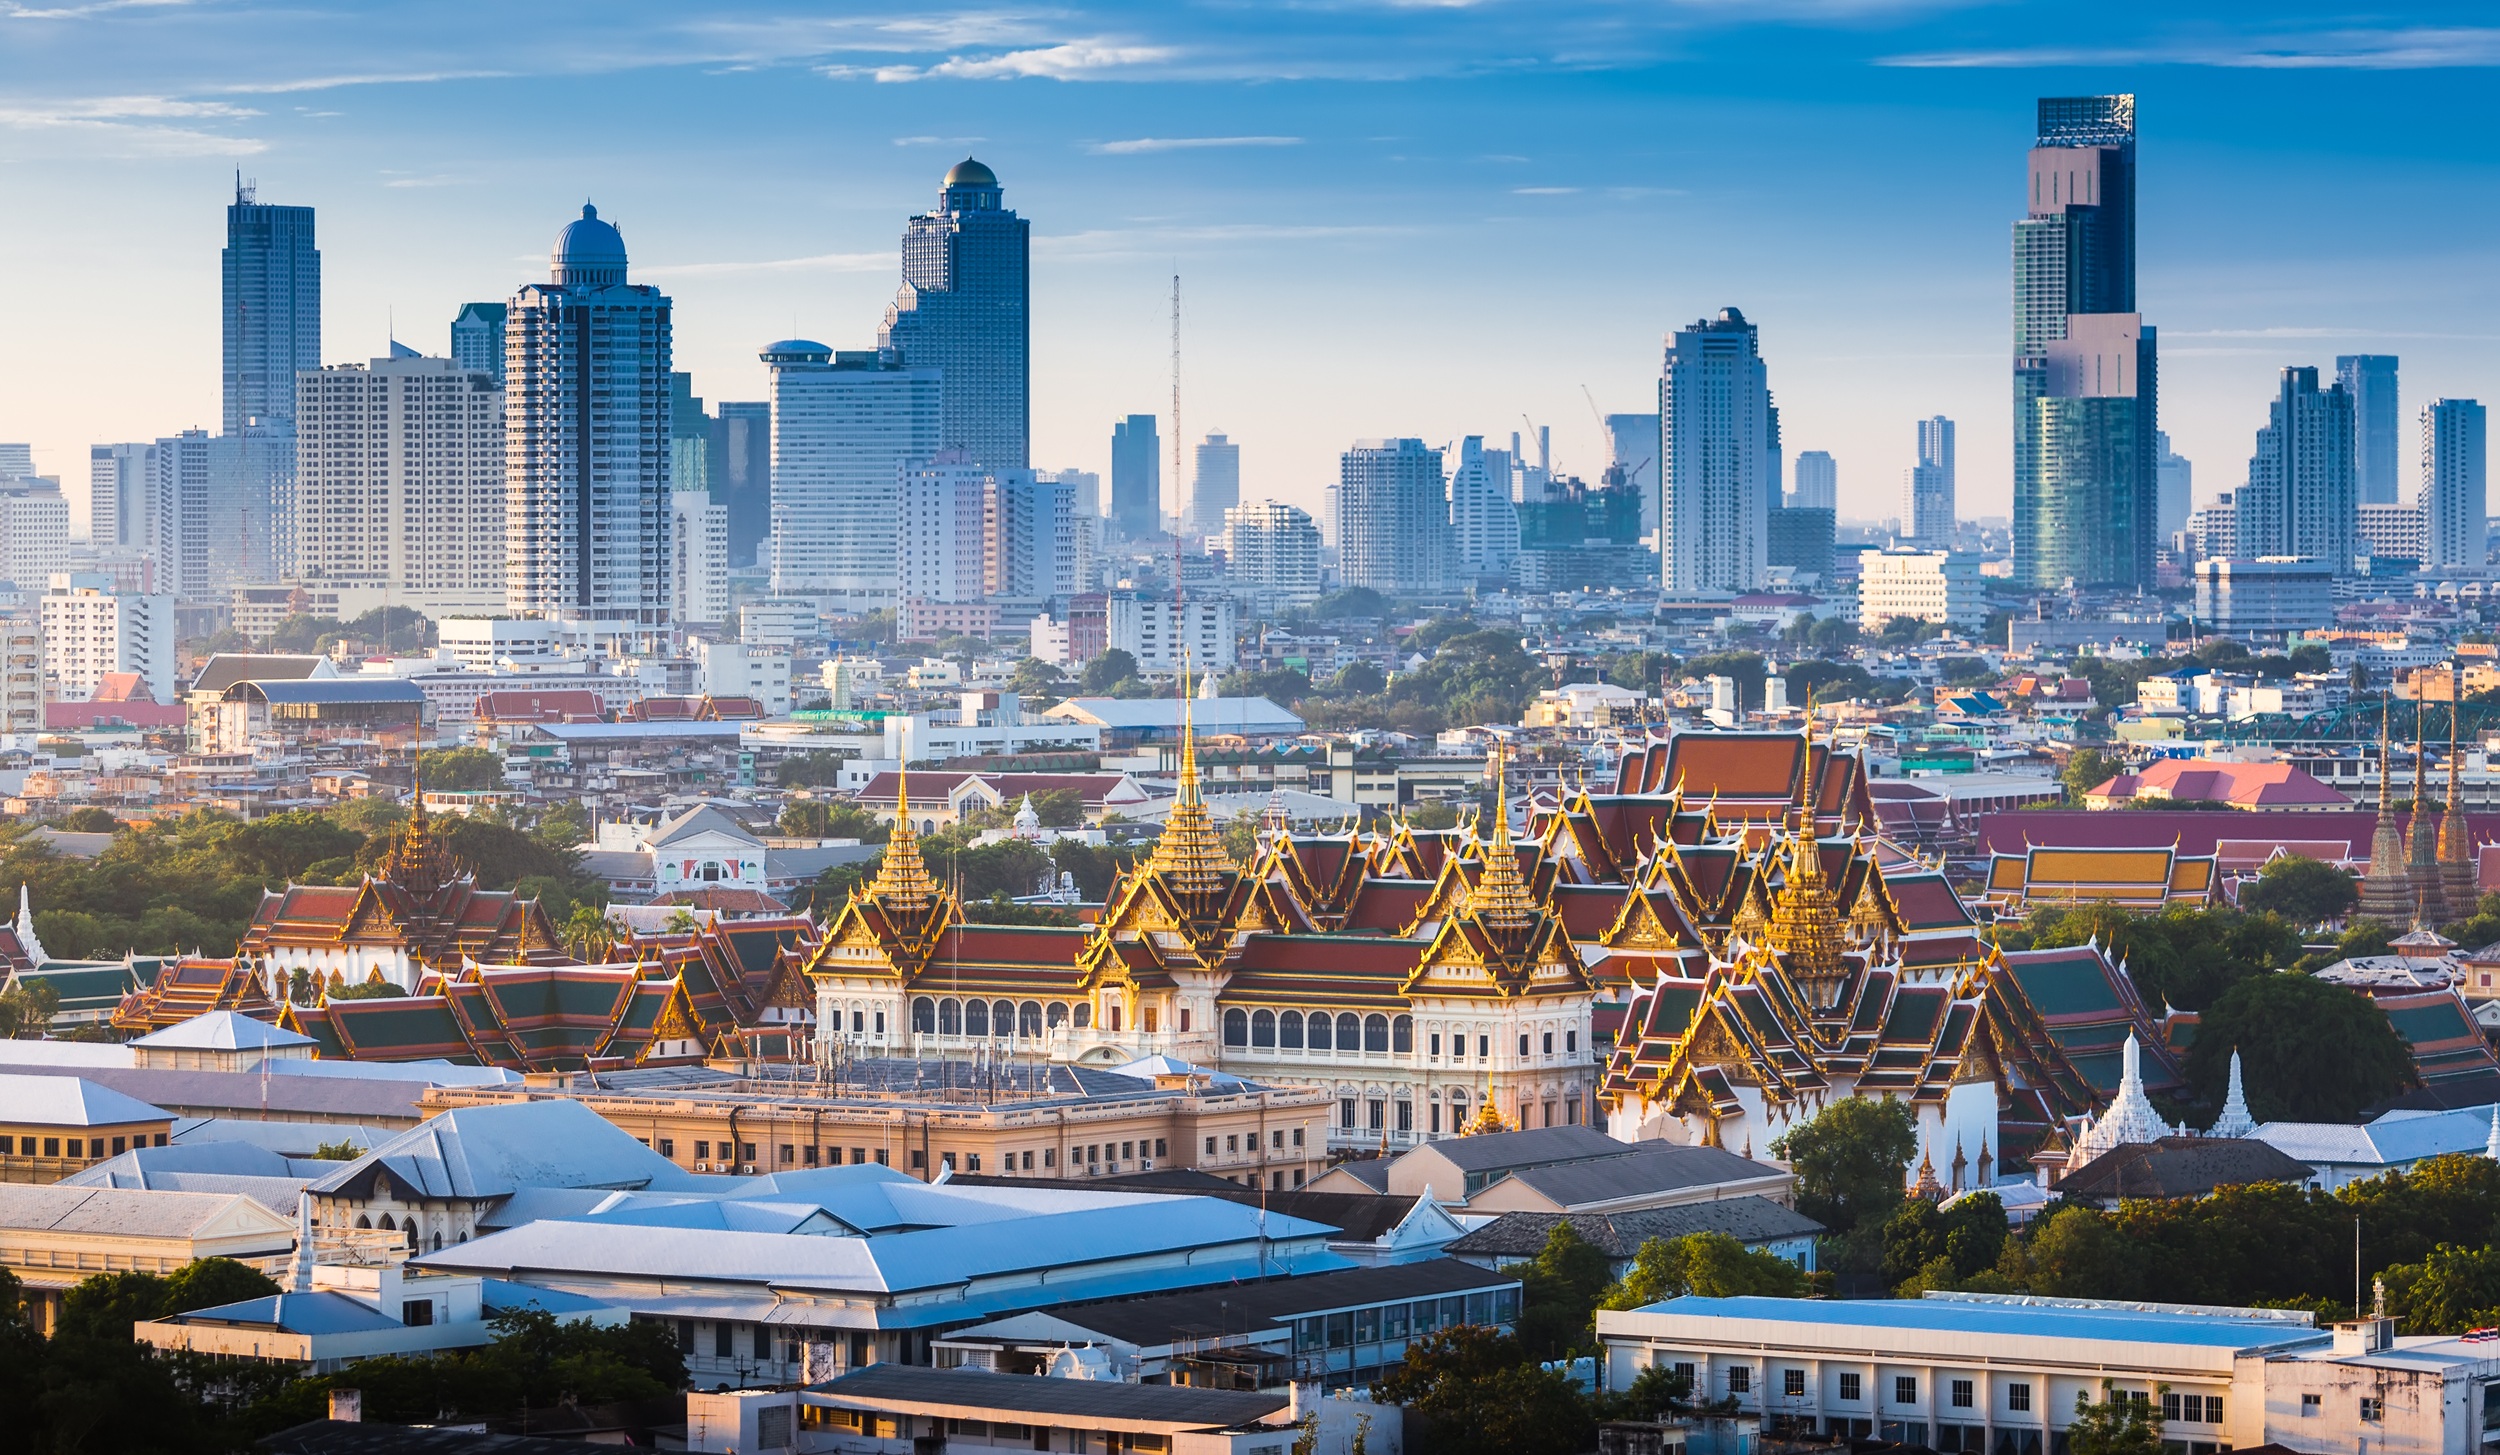
Transfer Pricing guide: Thailand
Read below for more detailed information on transfer pricing regulations, document requirements, and other considerations for Thailand, as well as recent industry hot topics and key developments in the country's business landscape.
Page updated 1st July 2026
Transfer Pricing regulations
Is the jurisdiction part of OECD/G20 Inclusive Framework on BEPS?
Yes.
Relevant Transfer Pricing regulation
- Departmental Instruction No. Paw 113/ 2545
- Director General’s Notification (DGN) Nos. 400, 407, 408, and 419
- Section 65 bis (4); Section 65 ter (15); Section 35 ter; Section 71 bis; and Section 71 ter of the Thai Revenue Code (TRC)
Is this regulation aligned with the OECD Guidelines
Yes.
Transfer Pricing documentation requirements
Documentation Threshold for Preparation of Local File/ TP Documentation
No specific threshold.
Documentation Threshold for Preparation of Master File
The Thai Revenue Department (TRD) has not issued any rules/ guidelines regarding the preparation/ submission of the Master File
Documentation Threshold for Preparation of Country by Country Report
Group consolidated revenue over Thai Baht (THB) 28 billion.
Submission of Local File, Master File, and CbC Report Required? If so, when?
- TP Local file must be provided to the TRD upon request.
- CbCR filing/ submission is required for companies/ juristic partnerships that are part of an MNE group and with consolidated group revenue of atleast THB 28 billion, as follows:
1. Within 12 months after the end of the accounting period for the following:
a. Thai-headquartered MNE group - an entity registered under Thai law and is the ultimate parent entity (“UPE”) of the group;
b. Surrogate parent entity (“SPE”) registered under Thai law – as appointed by the MNE group to file the CbCR on behalf of the UPE.
2. Within sixty (60) days after receiving a written notice from the Thai Revenue Department assessment officer for entities carrying on business in Thailand, which are neither the UPE or SPE, and meet one of the following conditions, are also required to file the CbCR:
a. The foreign UPE of the MNE group is not required to file the CbCR in its tax jurisdiction, and the UPE did not appoint an SPE;
b. The foreign UPE or SPE of the MNE group does not have a multilateral competent authority agreement (“MCAA”) with Thailand, or such MCAA is not yet effective for the relevant accounting period; or
c. There exists a systematic failure of exchange of information from the residence jurisdiction of the UPE or SPE.
- Notifying CbCR filing to TRD
Can be done through:
- TP Disclosure Form – within 150 days after financial year-end (TP Disclosure Form deadline)
- TRD’s CbCR System – within 12 months after financial year-end
If No Submission Required, any Other Deadline?
TP Local file must be submitted to the TRD within 60 days upon request, and this deadline can be extended to 120 days at the discretion of the tax officer. Also, for a first-time request from the TRD, the submission period may be extended up to 180 days.
Other Documentation Requirements
TP local file can be prepared in English but needs to be provided to TRD in Thai language.
Does TP documentation / Local file Need to be Prepared Contemporaneously with Tax Return Filing (i.e., before filing the return)?
Yes.
Transfer Pricing Specific Returns
Preparation of TP Return Required?
TP Disclosure Form.
Deadline for TP Return Filing
Within 150 days after end of financial year (plus 8 days for online filing)
Key information to be included in the TP Return
Part A: List of related parties
Part B: Summary of related party transactions (income/ expenses/ loans)
Part C: Other information - CbcR notification
Benchmarking - Local Tax Authority Preferences
Local vs Regional Comparables Set
The RD prefers local comparable sets. However, regional comparable sets can be used where local comparables sets are not available.
Single-Year vs Multi-Year Analysis
Multi-year analysis
Public vs Private Comparables
N/A
Interquartile Range or Full Range
Interquartile Range is required.
Transaction-Based or Aggregate Approach, or Both
No rules prescribed in the Thai TP regulations
How Often are Benchmarking Sets Renewed (financial update versus full scope BMS preparation)
In line with the OECD guidelines, a new search must be performed every 3 years, provided the taxpayer meets stipulated conditions pertaining to tested related related party transaction(s).
TP Penalties
In Case of Delayed Submission of Documentation
Penalty for incomplete documentation, failure/ late submission, or incorrect disclosure may be imposed up to THB 200,000
In case of Income Adjustments in Course of a Tax audit
- In case adjustments are made to the taxable income voluntarily, in addition to the additional tax payable, a surcharge of 1.5% per month or part thereof, capped at 100% of the additional tax payable, would be imposed.
- However, where the TRD issues a notice of assessment, a penalty of 100% of the additional tax payable would also be payable in addition to the additional tax and surcharge.
Other Considerations
APA & MAP Availability
Bilateral/ Multilateral APA and MAP are available
Applicability of Safe Harbour Rules
Not available in Thai TP regulations
Critical Transfer Pricing Issues Prevailing in the Jurisdiction, if any
Intragroup services
- Centralised back-office functions (e.g., IT, legal, finance, R&D) are typically provided by the parent company, group service center, or head office;
- TRD widely viewed this transaction as a profit extraction measure;
- The recipient and provider must prove need, benefit, rendition, non-duplication, and non-stewardship tests
- Services may be considered as “low value-added services” by the TRD, and a higher mark-up on costs cannot substantiate the arm’s length principle
Royalty payments
- Generally paid for the use and exploitation of a licensed intellectual property (IP) ;
- TRD views this transaction as a tool for tax base erosion on account of excessive or misaligned royalty payments;
- Royalty payments should align with the value of the IP (based on the economic contributions made by group entities to develop such IP), such as patents, trademarks, and technical know-how.
Criteria/ Guidelines for Transfer Pricing Audit/ Assessments by Tax Authority
Currently, tax officers are focusing more on conducting TP audits by using the TP Disclosure Form as a tool to select cases for audit. Moreover, the TRD, in many recent cases, has questioned benchmarking analyses that have not used local comparable sets.
Relevant Regulations and Rulings with Respect to Thin Capitalization or Debt Capacity in the Jurisdiction
Not yet introduced in Thai TP regulations to date
Meet the experts
Wherever your business operates, HLB's specialists combine local expertise with global collaboration to deliver practical advice, helping organisations navigate challenges, seize opportunities and achieve their ambitions.
February 2025: Thailand enacts Top-up Tax Emergency Decree to implement OECD’s BEPS 2.0 Pillar Two (effective for fiscal years beginning on or after 1 January 2025)
April 2024: The Thai Revenue Department (“TRD”) issued rulings viz. Kor Kor 0702/1978, Kor Kor 0702/ 217 and Kor Kor 0702/ 3356, adjudicating that companies can be considered related parties under Section 71 bis of the Thai Revenue Code (“TRC”) if a group of individual shareholders collectively holds more than 50% of shares in both entities, even if no single shareholder holds a majority stake. This interpretation emphasizes that collective shareholding can establish a related-party relationship, impacting TP disclosure obligations.However, a contrary view to the above can be that the provisions of Section 71 bis of the TRC do not permit the TRD, suo moto, to treat the group of individual shareholders as constituting a controlling group, especially where there is no agreement for them to act in concert.October 2023: The TRD released new Advance Pricing Agreement (“APA”) Guidelines, which provide instructions/ requirements for bilateral APAs, i.e., information required to be included in the application
January 2022: TRD released Director General’s Notification (“DGN”) 419 for the filing/ submission of CbCR with the online system
October 2021: TRD released DGN 408, introducing Country-by-country report (“CbCR”) reporting requirements (effective for fiscal years beginning on or after 1 January 2021)
September 2021: TRD released DGN 407 with requirements for the TP Local File (effective for fiscal years beginning on or after 1 January 2021)
January 2021: The TRD released DGN 400, prescribing TP rules and procedures
When can the TRD initiate the audit?
As per Section 71 ter of the TRC, the TRD can initiate a TP audit within five years from the date of submitting the TP Disclosure Form.
Additionally, under Section 19 of the TRC, the tax officer must issue a summons for investigation within 2 years from the date the tax return was filed. However, this can be extended up to 5 years if there is evidence of tax avoidance or if the case involves a tax refund, with approval from the Director-General.
Time to comply
Within 60 days of receiving the notification from TRD. For those who receive the notification for the first time, compliance must be within 180 days of receiving the notice.
Broad criteria of the TRD for selecting companies for audit/ assessments:
- Consistently incurring losses for several consecutive years;
- Inconsistent business performance;
- Earning profits lower than the industry average;
- Incurring losses after the expiration of the BOI investment promotion (for availing tax benefits) period;
- Changing business structure resulting in reduced net profit or losses;
- YoY significant increase in payment of management fees, royalties, etc. to related companies; and
- Lack of supporting documents and evidence to support transactions with related parties.
Currently, the RD has been focusing more on TP audits by using the TP Disclosure Form as a tool to select potential cases for audit.
APA Availability
A company or juristic partnership incorporated under Thai law that engages in intra-group transactions with affiliates who are residents of Thailand’s treaty partners may apply for an APA by submitting a written proposal directly to the Director-General of the TRD. Only Bilateral APAs are accepted in such cases.
If the taxpayer intends to apply the APA terms and conditions to accounting periods prior to those covered by the APA (i.e. ‘Roll Back period’), it must clearly state this intention and justify at the time of application. If a translator or subject matter expert is required during the APA process, the responsibility for arranging and bearing the cost lies with the taxpayer.
An APA typically covers a period of three to five accounting years. Importantly, the last day of the first covered accounting period must fall on or after the date the APA application is submitted. If the taxpayer requests to include the ‘Roll Back’ period, the Roll Back may be granted for up to two prior accounting periods. However, this is subject to the specific facts and circumstances of each case.
MAP Availability
A taxpayer who is a resident of Thailand, as defined under the applicable Avoidance of Double Taxation Agreement (“DTA”), is eligible to request a MAP from the Thai Competent Authority (i.e. Director-General of the TRD) in accordance with the MAP article of the relevant DTA.
This request may be made when the taxpayer believes that actions taken by one or both Contracting States have resulted, or will result, in taxation not as per the provisions of the DTA. Accordingly, the TRD will only accept MAP requests submitted by taxpayers who are considered Thai residents under the relevant DTA.
A taxpayer may submit a MAP request regardless of the availability of domestic remedies under the internal laws of either Contracting State. Submitting a MAP request does not prevent the taxpayer from pursuing other legal remedies, such as appealing tax assessments or actions taken by the tax authorities, as provided under the respective domestic laws to protect against unlawful taxation. This applies only to administrative appeals. Once a court decision becomes final, it is binding, and the TRD cannot enter into a MAP agreement that results in taxation contrary to the court’s ruling, even if such agreement is more favourable to the taxpayer.
The issuance of a court ruling on the case related to the MAP request does not, in itself, prevent the initiation of a MAP. However, due to the binding nature of Thai court decisions, the Thai Competent Authority cannot adopt a position or implement an agreement under MAP that would deviate from a final court ruling that has entered into force.
Alignment with OECD Guidelines
Thai TP regulations are broadly in line with OECD Guidelines.
Annual statutory compliance requirements
- Maintenance of TP documentation (local file): To be prepared annually on a contemporaneous basis.
- TP Disclosure Form: To be submitted online to TRD within 150 days from the end of the financial year (for Thai companies with annual revenue of at least THB 200 million during the financial year)
- CbCR: If filed in a country other than Thailand, then the TRD needs to be notified/ informed about the same. Thai-headquartered MNE needs to file CbCR if such MNE crosses the prescribed revenue threshold (i.e., THB 28 billion).
- Master file: No rules enacted by TRD in this relation so far.
Benchmarking analyses, nuances, or preferences
The TRD strongly prefers the use of Thai comparables. However, regional comparables may be used where Thai comparables are either unavailable or insufficient. Where regional comparables are used, the TRD has rejected the benchmarking analysis in the past and required an analysis to be undertaken using Thai comparables. Accordingly, it will be necessary to justify the use of a regional comparables dataset.
Penal provisions
TP Documentation: Penalty for incomplete documentation, failure/ late submission, or incorrect disclosure may be imposed up to THB 200,000 (discretion by the TRD on justification).
In case adjustments are made to the taxable income voluntarily, in addition to the additional tax payable, a surcharge of 1.5% per month or part thereof, capped at 100% of the additional tax payable, would be imposed. However, where the TRD issues a Notice of Assessment, a penalty of 100% of the additional tax payable would also be payable in addition to the additional tax and surcharge.
TP Disclosure Form
Penalty for failure to submit within 7 days after the due date: Fine THB 50,000. More than 7 days after the due date: Fine THB 100,000. Detected by TRD officer: Fine THB 200,000
CbCR
A general fine of THB 2,000 would apply for failure to lodge the CbCR by the due date.There is no specific penalty regime for the failure to comply with the CbCR reporting requirements. The THB 2,000 fine is issued under Sections 17 and 35 of the TRC.